TaxTrack guide · Updated September 24, 2026
S corporation owners: what you owe South Carolina, and what the company owes
Short answer: An S corporation usually pays no South Carolina income tax on profit that passes through to its owners; each owner reports their share on a personal return and pays South Carolina individual income tax there. The corporation still files an SC1120S every year and owes its license fees, and it must withhold 5% for owners who live outside South Carolina unless an exception applies.
Seeing the corporation and the owner as two separate taxpayers makes an S corporation cleanup far easier to plan, because each side has its own returns, its own balance and its own next steps.
How the money flows
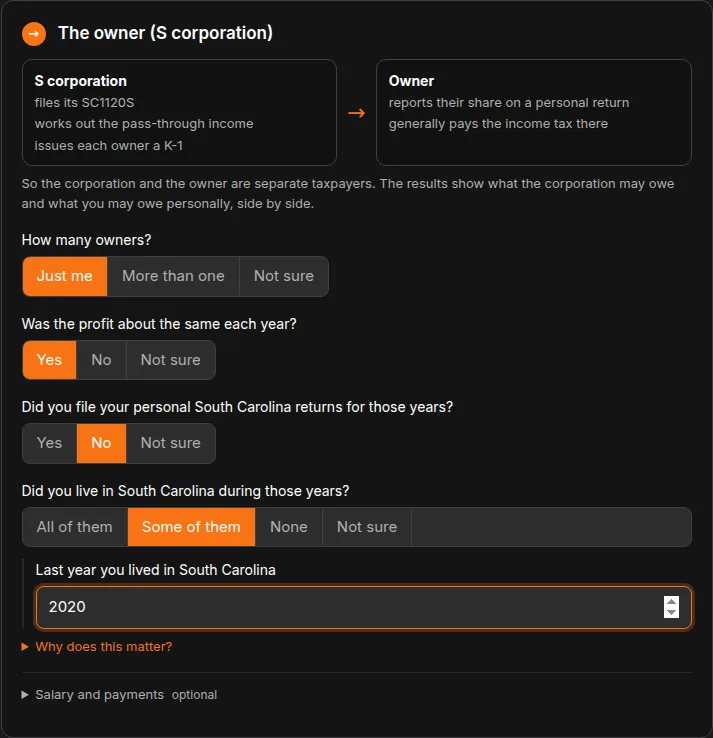
The S corporation files its SC1120S, works out the pass-through income and issues each owner a K-1. Each owner reports that share on a personal return and generally pays the income tax there. SCDOR says the SC1120S is due every year regardless of income or business, and the 5% corporate rate applies only to income actually taxed at the S corporation level.
South Carolina individual income tax rates by year
The owner's tax depends on the rules for each year, not today's rate. SCDOR publishes these top marginal rates:
| Tax year | Top rate |
|---|---|
| 2021 and earlier | 7% |
| 2022 | 6.5% |
| 2023 | 6.4% |
| 2024 | 6.2% |
| 2025 | 6% |
| 2026 | 1.99% under $30,000; 5.21% minus $966 from $30,000 |
TaxTrack applies each year's published top rate to the owner's share and labels the result preliminary, because full bracket tables, deductions, filing status and other household income can lower it.
Owners who live outside South Carolina
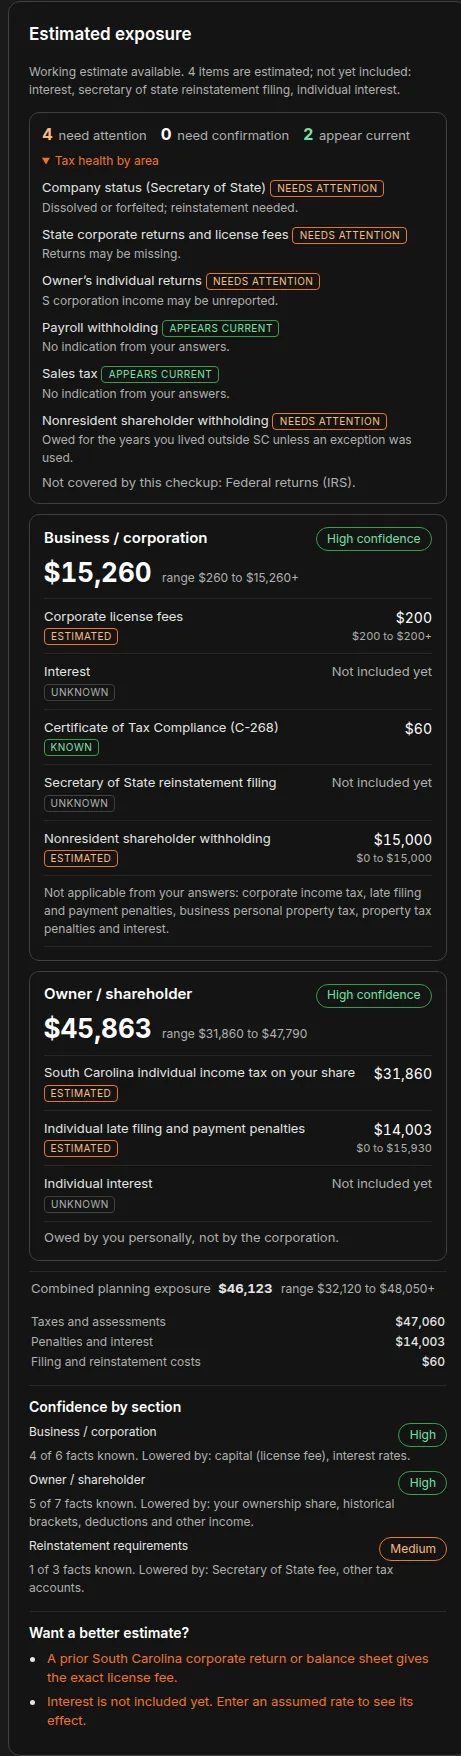
SCDOR requires an S corporation to withhold 5% of the South Carolina taxable income of shareholders who are nonresidents, unless the shareholder participates in a composite return, files an I-309 affidavit with the corporation, or is tax-exempt. That withholding is the corporation's obligation, and it counts toward the owner's own South Carolina tax.
Three situations, three next steps
- The corporation filed but the owner did not: the K-1 income still needs to go on the owner's personal returns.
- Neither filed: the S corporation returns come first, because they produce the K-1 figures the personal returns need.
- The owner filed without the K-1 income: that usually means amending those returns once the S corporation figures are known.
Run your own numbers, free
Answer what you know and TaxTrack estimates the rest: taxes, penalties, property tax, the owner side of an S corporation, and the steps back to good standing. Sign in with just your email.
Start the free checkupCommon questions
Does an S corporation pay South Carolina income tax?
Only on income taxed at the S corporation level, at 5%. Income that passes through to the owners is taxed on their personal returns.
What is the nonresident shareholder withholding rate in South Carolina?
5% of the South Carolina taxable income of nonresident shareholders, unless the shareholder is in a composite return, files an I-309 affidavit, or is tax-exempt.
Does the corporation owe the owner’s personal income tax?
No. The owner’s South Carolina individual income tax on their share is the owner’s own liability. TaxTrack shows it separately from the business.
Sources
Sources checked September 24, 2026.
Not tax, legal or accounting advice. TaxTrack by ExpenseTrack gives estimates for general information and planning only. It estimates and organizes; it does not prepare or file returns. Actual tax, penalties, interest and reinstatement requirements are determined by the South Carolina Department of Revenue, county offices and the Secretary of State. Talk to a qualified CPA, enrolled agent or tax attorney about your situation.